Navigating the Debt vs. Investment Dilemma in a High-Interest Environment
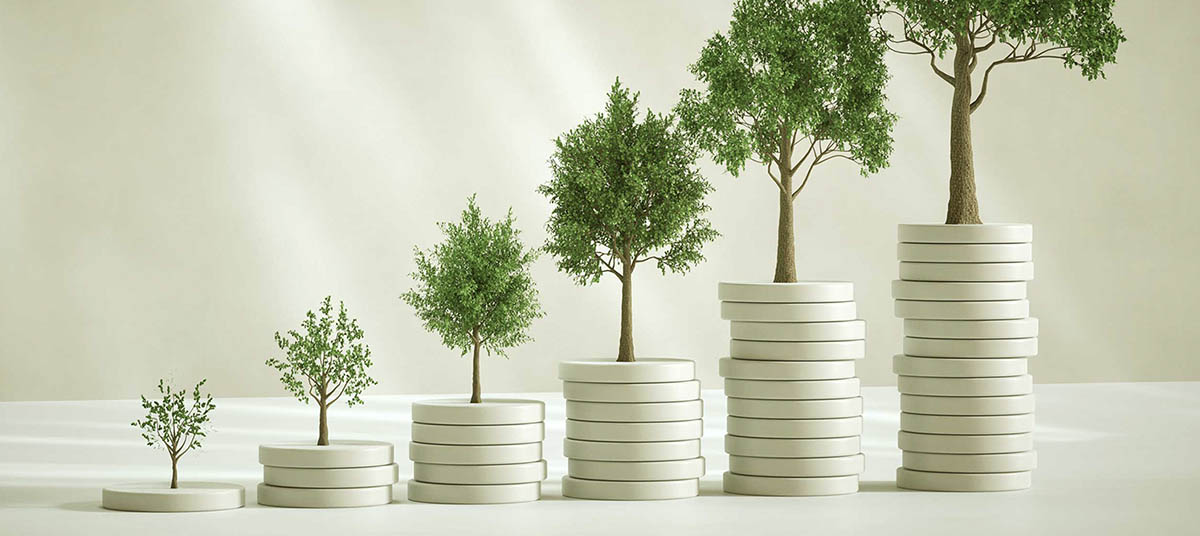
For a long stretch of recent history, the financial playbook seemed remarkably clear-cut. When interest rates hovered at historic lows and the stock market consistently rewarded patient, long-term investors, the prevailing wisdom leaned heavily in one direction. Most financial professionals advised keeping your extra capital in the market rather than rushing to pay down low-rate liabilities.
This strategy was highly effective in an era when home mortgages could be secured near three percent and traditional savings accounts yielded negligible returns. It made simple mathematical sense to leverage cheap debt while letting your investments seek higher returns elsewhere.
Today, however, the economic backdrop has transformed dramatically, requiring a much more deliberate approach to cash flow management.
The Core Dilemma: Balancing Debt Repayment Against Investment Growth
With credit card interest rates frequently climbing past the twenty percent mark, the cost of carrying consumer debt has soared. Similarly, auto loans, personal financing, and home equity lines of credit have grown substantially more expensive over a short period. Conversely, safer financial instruments like high-yield savings accounts and certificates of deposit are once again offering tangible, competitive yields. At the same time, many property owners continue to hold fixed-rate mortgages locked in at the rock-bottom rates of previous years—rates that are unlikely to return anytime soon.
This stark divergence has turned a formerly simple financial calculation into a complex, multi-layered question: Should you focus on eliminating your debt, or should you continue investing for the future?
There is no universal solution to this puzzle. The optimal strategy depends entirely on a unique combination of variables, including your current cash flow, household income, tax bracket, outstanding liabilities, risk appetite, and long-term financial targets. At Tangible Accounting, PLLC, we believe that understanding how these elements interact is key to making sound financial choices.
Prioritizing High-Interest Liabilities First
It is essential to recognize that not all outstanding liabilities carry the same financial weight. If your balance sheet includes credit card debt or other high-rate consumer obligations, focusing your financial energy on paying down those balances is often one of the most immediate ways to improve your overall cash flow position.
The reasoning is simple: every dollar you redirect toward wiping out high-interest debt provides a guaranteed, tax-free return equal to the interest rate you are avoiding. For most households, eliminating a twenty percent interest burden offers a far more predictable and immediate benefit than hoping for equivalent gains in the volatile financial markets.
Rather than viewing debt reduction and long-term investing as entirely separate or competing priorities, it is far more constructive to analyze how debt repayment fits into your comprehensive financial plan, keeping in mind your emergency reserves, retirement goals, and tax considerations.
The Nuanced Strategy Behind Managing Low-Interest Obligations
Conversely, not all borrowing needs to be cleared at an accelerated pace. Many individuals still hold fixed-rate home mortgages that were established or refinanced during the period of historically low rates. If you are fortunate enough to have a mortgage rate that sits significantly below today's current borrowing and investment yields, it is highly beneficial to assess whether your surplus cash would serve you better in other areas.
Rather than making extra principal payments on a very low-rate loan, you might find greater value in executing other financial moves, such as:
Strengthening your liquid cash reserves for emergencies.
Boosting your annual contributions to retirement accounts.
Securing any matching contributions offered by your employer.
Maintaining a higher degree of overall financial flexibility.
Continuing to fund dedicated, long-term investment vehicles.
Ultimately, the right course of action is determined by the entirety of your financial landscape, not just a single interest rate on a single loan.
Why a Robust Emergency Fund Remains Non-Negotiable
One of the most frequent financial missteps is funneling every spare dollar into debt repayment while leaving yourself without a cash safety net. Life rarely moves in a straight line, and unexpected financial demands are inevitable.
Whether you are faced with a sudden career transition, major residential repairs, unforeseen medical expenses, or urgent vehicle maintenance, a lack of liquid cash can quickly disrupt your financial plan. Without a dedicated emergency fund, many households are forced to rely on high-interest credit cards to handle these unexpected events. This often undoes the hard-won progress made during your debt-repayment push.
By establishing and maintaining a robust emergency fund, you build a vital buffer that protects your financial stability and reduces your reliance on high-cost borrowing when challenges arise.
Analyzing the Tax Implications of Saving and Debt Management
Deciding between debt reduction and investing goes beyond a simple comparison of raw interest percentages. The tax code introduces variables that can significantly shift the math in either direction.
Different accounts carry distinct tax advantages that must be factored into your decision:
- Traditional retirement accounts can offer an immediate, current-year tax deduction, allowing your underlying investments to compound on a tax-deferred basis until withdrawal.
- Roth retirement accounts are funded using after-tax dollars, meaning you do not receive an immediate deduction, but qualified future withdrawals can be completely tax-free.
- Taxable investment accounts provide maximum liquidity and access to your money, but they do expose you to annual taxes on interest, dividends, and realized capital gains.
In addition, the tax treatment of the interest you pay must be evaluated. Certain types of borrowing, such as qualifying residential mortgage interest or interest associated with business operations, may be tax-deductible depending on your personal tax profile and filing status. Examining these decisions through a dual tax and financial lens ensures you are seeing the complete picture before moving forward.

Capitalizing on Employer-Sponsored Retirement Plan Matches
If your employer provides matching contributions to a workplace retirement plan, this is an incredibly powerful tool that should never be ignored. An employer match is essentially an immediate, guaranteed return on your contributed dollars, which can significantly multiply your long-term savings potential. This benefit should heavily influence how you rank your financial priorities alongside any debt repayment strategies. Rather than treating these choices as isolated decisions, look at how workplace benefits can serve as a primary pillar of your wealth-building strategy.
A Structured Financial Framework for Decision-Making
While every household's situation is distinct, many seasoned advisors suggest a structured, step-by-step approach to balancing your competing financial demands:
Establish an initial, modest emergency reserve to handle minor, unexpected expenses.
Contribute enough to your employer's retirement plan to capture the maximum available matching funds.
Target and systematically reduce high-interest debt balances.
Continue building and reinforcing your primary emergency cash reserves.
Increase your regular contributions to retirement accounts and other long-term investment vehicles.
Regularly evaluate whether making extra payments on low-interest liabilities aligns with your broader financial objectives.
This sequence is not a rigid, unyielding rule. Instead, it serves as a highly practical framework designed to guide productive discussions about balancing cash flow, savings, investment growth, and long-term financial peace of mind.
How the Modern Interest Rate Climate Alters the Equation
The current macroeconomic environment has redefined how we must approach basic financial choices. In the past, when savings yields were virtually non-existent, there was very little financial incentive to keep cash sitting in a bank. Today, the ability to earn competitive yields on certificates of deposit and high-yield savings accounts allows you to generate meaningful returns while retaining high liquidity. This does not diminish the long-term value of traditional investing; rather, it highlights that the rules have evolved, and strategies that served you well several years ago may need to be updated to match today's realities.
Essential Questions to Guide Your Financial Strategy
Before committing your capital to a specific path, take the time to evaluate these fundamental questions:
What are the exact interest rates on my current liabilities?
Do I have an adequate cash cushion to handle an unexpected financial shock?
Am I taking full advantage of any employer-matched retirement contributions?
How will my choices affect my overall annual tax liability?
What are my core, long-term personal and financial milestones?
Will this choice enhance or restrict my day-to-day cash flow flexibility?
Asking the right questions upfront is the best way to ensure your decisions support your long-term goals.
Embracing a Balanced Approach Over Single-Track Strategies
A common misconception in personal finance is the belief that you must select a single, exclusive strategy—either focusing entirely on debt elimination or focusing solely on asset accumulation. In practice, the most resilient financial plans incorporate a balanced mix of several priorities simultaneously. Depending on your current cash flow, this balanced approach might involve:
Consistently building your emergency savings.
Systematically chipping away at high-rate debt.
Making steady, disciplined contributions toward retirement.
Maximizing any available workplace retirement matching programs.
Periodically reviewing low-rate debt within the context of your broader financial outlook.
The ultimate objective is not to find a single, magic answer, but to design a dynamic strategy that adapts as your life and the broader economy change.
Structuring a Custom Financial Path for Long-Term Security
Successful financial management is never about forcing your life into a generic formula. It is about making deliberate, well-informed decisions that reflect your cash flow, family requirements, tax situation, and ultimate goals. What works perfectly for one household may not be the right path for yours. That is why consistently reviewing your plan is so vital—especially as tax regulations, interest rates, and personal circumstances shift over time.
Your choices regarding debt repayment, retirement savings, investment allocations, and tax planning are deeply interconnected. Before making any major adjustments, contact Tangible Accounting, PLLC to explore the tax implications and ensure your strategy is fully optimized. Led by Enrolled Agent Jaron J. Fulse, our team stands ready to collaborate with you—and work alongside your designated financial advisor—to ensure all aspects of your tax and financial planning are perfectly aligned.
Want tax & accounting tips and insights?
Sign up for our newsletter.
Affiliations
See why our clients love us!

Brian B.

E S.

Monty

Christine O.

Mai A.

stephanie R.

L W.

Ronald S.
Kim C.
Damion T.

Damion T.
